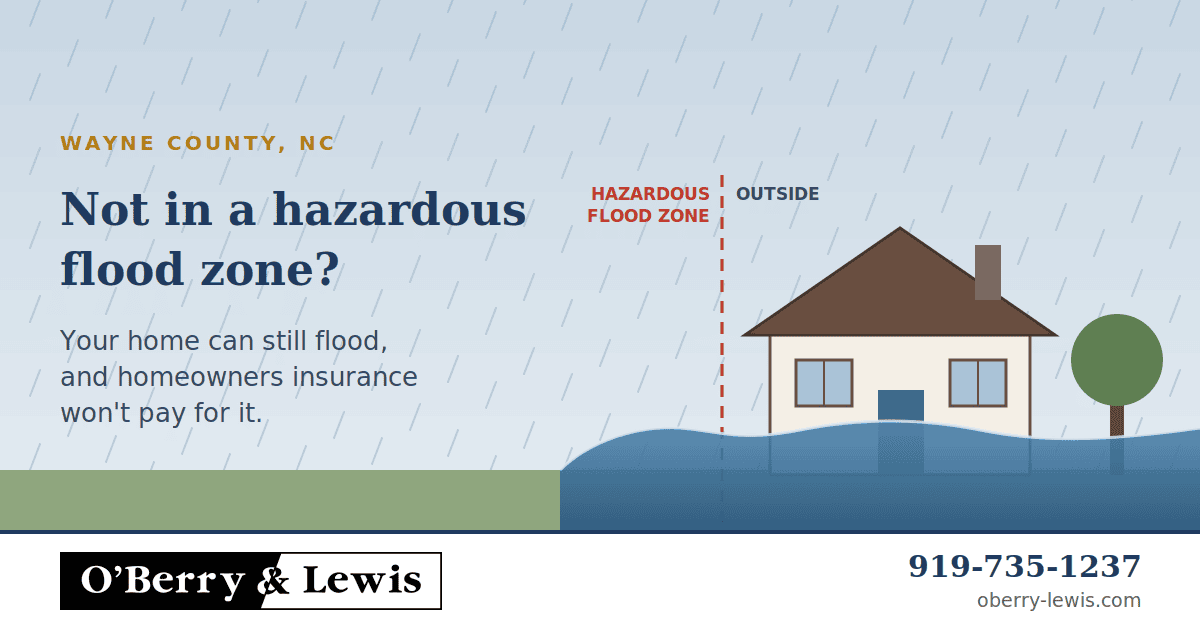
If you live anywhere near the Neuse River, Little River, or a creek in Wayne County, you should strongly consider flood insurance, even if you’re not in a hazardous flood zone. Your homeowners policy does not cover flood damage. Not “partly” or “with a deductible”: flooding is excluded outright.
The flood zone on your mortgage paperwork only tells you whether your lender requires flood insurance. It doesn’t tell you whether your house can flood. According to FEMA, about one-third of flood insurance claims come from properties outside the high-risk zones.
Here’s what most people get wrong: every property in Wayne County sits in some flood zone. “Not in a hazardous flood zone” just means you’re in a lower-risk zone, not a no-risk zone. And lower risk is exactly why the coverage is cheaper there.
How often does Wayne County flood?
More than the maps suggest. In the last 30 years, the Neuse River at Goldsboro has set or come close to its record three times:
Storm
Year
Neuse River crest at Goldsboro
Hurricane Floyd
1999
27.71 feet
Hurricane Matthew
2016
29.74 feet (record)
Hurricane Florence
2018
27.6 feet
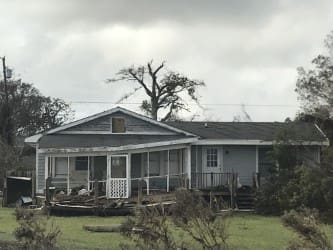
Matthew dropped 14 to 18 inches of rain on the Goldsboro area in a single weekend. Wayne County and Goldsboro reported 125 water rescues. Two years later, Florence dropped just under 15 inches of rain on Goldsboro, even though it sits about 100 miles from the coast.
Why homes outside the hazardous flood zone still flood
-
Flood maps show river flooding, not every flood. When 15 inches of rain falls in a day or two, ditches, culverts, and storm drains back up. Water gets into houses far from any river.
-
Maps age. Every new subdivision, parking lot, and paved road changes where water goes, and maps aren’t redrawn every year.
-
The line is a guess, not a wall. A house 200 feet outside a high-risk zone faces almost the same water as the one 200 feet inside it.
If your street flooded during Matthew or Florence, assume it can flood again, whatever the map says.
What does flood insurance cover?
Most flood policies in North Carolina are written through the National Flood Insurance Program (NFIP), which is run by FEMA and sold through local agents like us. A standard NFIP policy has two separate parts:
Coverage
Maximum
What it pays for
Building
$250,000
Structure, foundation, electrical, plumbing, HVAC, water heater, built-in appliances, flooring
Contents
$100,000
Furniture, clothing, electronics, washer and dryer
Contents coverage is not automatic. You have to add it. Many homeowners only buy building coverage, then learn after a flood that their furniture and belongings weren’t covered.
Two other things to know:
-
Crawl spaces and basements get limited coverage. Items like your furnace and ductwork are covered, but finished areas and stored belongings mostly aren’t.
-
Private flood insurance is an option for many Wayne County homes, often with more coverage and a shorter wait. More on that below.
Private flood insurance: higher limits, shorter waits
O’Berry & Lewis writes flood coverage with multiple private flood markets, not just the NFIP. If your home qualifies, a private policy can fix the two biggest weaknesses of a federal flood policy:
-
Higher limits. NFIP building coverage stops at $250,000. Private markets can insure your home closer to its full rebuilding cost, which matters for larger or newer homes where a rebuild runs well past $250,000.
-
Shorter waiting periods. Many private flood policies take effect sooner than the NFIP’s 30 days, depending on the carrier. That can close the gap if you’re buying ahead of hurricane season.
Private policies also aren’t tied to the NFIP’s reauthorization deadlines, so a lapse in Congress doesn’t stop you from buying one.
Not every home qualifies. Private carriers look at location, elevation, and flood history. When your home does qualify, we’ll quote private and NFIP options side by side so you can compare price and coverage.
How much does flood insurance cost outside a hazardous flood zone?
Usually much less than people expect, but there’s no single price. FEMA now rates each home individually, using factors like distance to water, elevation, foundation type, and rebuilding cost, instead of relying only on the flood zone.
That cuts both ways. A home on high ground far from water may be quite affordable to insure. A home in a low spot near a creek may cost more than the zone alone would suggest. The only way to know is to get a quote for your specific address.
Don’t wait for a storm: the 30-day rule
A new NFIP policy generally doesn’t take effect until 30 days after you buy it. You can’t buy flood insurance when a hurricane shows up in the forecast and expect it to cover that storm.
There’s a second timing issue right now. Congress keeps the NFIP running with short-term extensions, and the current one runs through December 11, 2026. When the program lapses, new NFIP policies can’t be issued until Congress acts. It has lapsed twice since October 2025. Private flood policies aren’t affected by a lapse, which is one more reason to compare both options now.
How to check your flood risk in Wayne County
-
Look up your address on the NC Flood Risk Information System at fris.nc.gov. It’s the state’s official flood map and shows your zone and nearby flood areas.
-
Think about what you’ve seen. Did your street, yard, or crawl space take water during Matthew, Florence, or a heavy summer storm?
-
Ask us for a quote. We’ll pull your property’s rating and compare NFIP and private options side by side.
Frequently asked questions
Does homeowners insurance cover flooding in North Carolina?
No. Standard homeowners policies exclude flood damage from rising water, overflowing rivers, and storm surge. You need a separate flood policy.
Is flood insurance required if I’m not in a hazardous flood zone?
Usually not. Lenders generally require it only in high-risk zones. But not being required isn’t the same as not being at risk.
Can renters buy flood insurance?
Yes. Renters can buy contents-only flood coverage for their belongings. Your landlord’s policy won’t cover your things.
Won’t FEMA disaster aid cover me if my house floods?
Don’t count on it. Disaster aid only comes after a federal disaster declaration, and it is usually far less than what it costs to repair a home. Much of it comes as loans you have to pay back.
How long does it take for flood insurance to start?
A new NFIP policy generally takes effect after a 30-day waiting period. There are exceptions, such as when the policy is required for a new mortgage. Many private flood policies have shorter waiting periods.
Talk to a Goldsboro agent about your flood risk
O’Berry & Lewis has served Wayne County and eastern North Carolina since 1927. We’ve been right here in Goldsboro through Floyd, Matthew, and Florence, and we’ll give you a straight answer about your property’s risk.
Call us at 919-735-1237 or stop by 200 E. Spruce St. in Goldsboro. A quote takes a few minutes, and the 30-day clock only starts once you buy.